• TRUSTED RESEARCH

    TRUSTED RESEARCH | STRATEGIC INSIGHT

    SMB. CORE MIDMARKET. UPPER MIDMARKET. ECOSYSTEM
    LEARN MORE
  • COMMS, COLLAB, CONTACT CENTER

    COMMS, COLLAB, CONTACT CENTER

    SMB & Midmarket Buyers Collaboration, Contact Center Study
    LATEST RESEARCH
  • DATACENTER SOLUTIONS

    DATACENTER SOLUTIONS

    SMB & Midmarket Datacenter Solution Adoption Trends
    LATEST RESEARCH
  • PARTNER ECOSYSTEM

    PARTNER ECOSYSTEM

    CHANNEL PARTNER ECOSYSTEM TRENDS STUDY
    LATEST RESEARCH
  • BUYER JOURNEY

    BUYER JOURNEY

    SMB & Midmarket Buyers Journey Research
    LATEST RESEARCH
  • BUYER PERSONAS

    BUYER PERSONAS

    SMB & Midmarket Technology Buyer Persona Research
    LATEST RESEARCH
  • ARTIFICIAL INTELLIGENCE

    ARTIFICIAL INTELLIGENCE

    SMB & Midmarket Analytics & Artificial Intelligence Adoption
    LATEST RESEARCH
  • IT SECURITY TRENDS

    IT SECURITY TRENDS

    SMB & Midmarket Security Solutions Adoption Trends
    LATEST RESEARCH
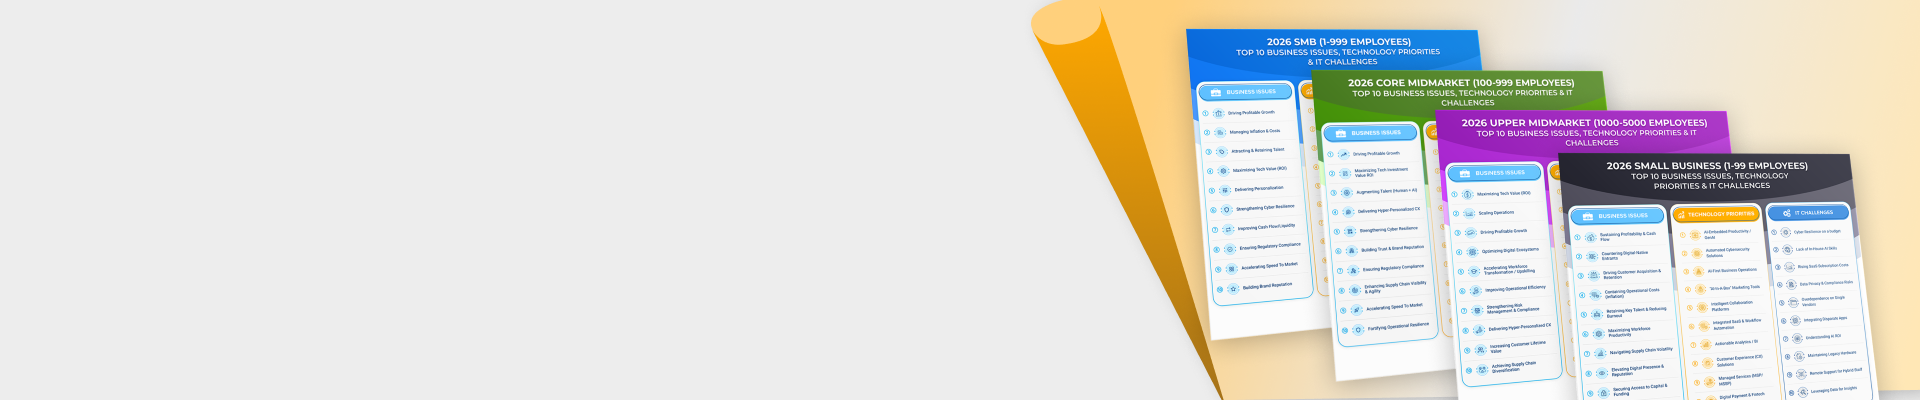
  • 2026 TOP 10 SMB BUSINESS ISSUES, IT PRIORITIES, IT CHALLENGES

    2026 TOP 10 SMB BUSINESS ISSUES, IT PRIORITIES, IT CHALLENGES

  • 2026 TOP 10 SMB PREDICTIONS

    2026 TOP 10 SMB PREDICTIONS

    SMB & Midmarket: Autonomous Business
    READ
  • 2026 TOP 10 PARTNER PREDICTIONS

    2026 TOP 10 PARTNER PREDICTIONS

    Partner & Ecosystem: Next Horizon
    READ

Techaisle Analyst Insights

Trusted research and strategic insight decoding SMBs, the Midmarket, and the Partner Ecosystem.
Anurag Agrawal

The Midmarket AI Fracture: Why the Infrastructure Supercycle Demands Full-Stack Orchestration

For decades, midmarket infrastructure procurement followed the hardware-aging cycle: IT departments replaced servers and switches as they depreciated. In the upper midmarket, that cycle has broken. According to the Techaisle SMB and Midmarket Datacenter Solutions Adoption Trends Research Report, 57% of the overall SMB market has a major infrastructure refresh underway or scheduled within 12 months, and in the upper midmarket the primary catalyst is now proactive workload enablement rather than hardware aging.

The data gravity of artificial intelligence is driving a hardware supercycle. 32% of upper midmarket firms are refreshing to meet new workload requirements, including AI, against 20% replacing hardware at end of life. In the core midmarket, end-of-life replacement still leads at 28%. The supercycle is creating distinct architectural tracks based on organizational maturity, and major ecosystem players such as Dell, Lenovo, Cisco, AWS, and Google Cloud need to reevaluate how they position their portfolios for each. The disjointed accumulation of isolated products has created an integration gauntlet, and midmarket customers are demanding cohesive, full-stack orchestration.

techaisle midmarket ai fracture

Anurag Agrawal

Gemini Becomes the Agent: Google Moves the Center of Gravity from Models to Governed Work

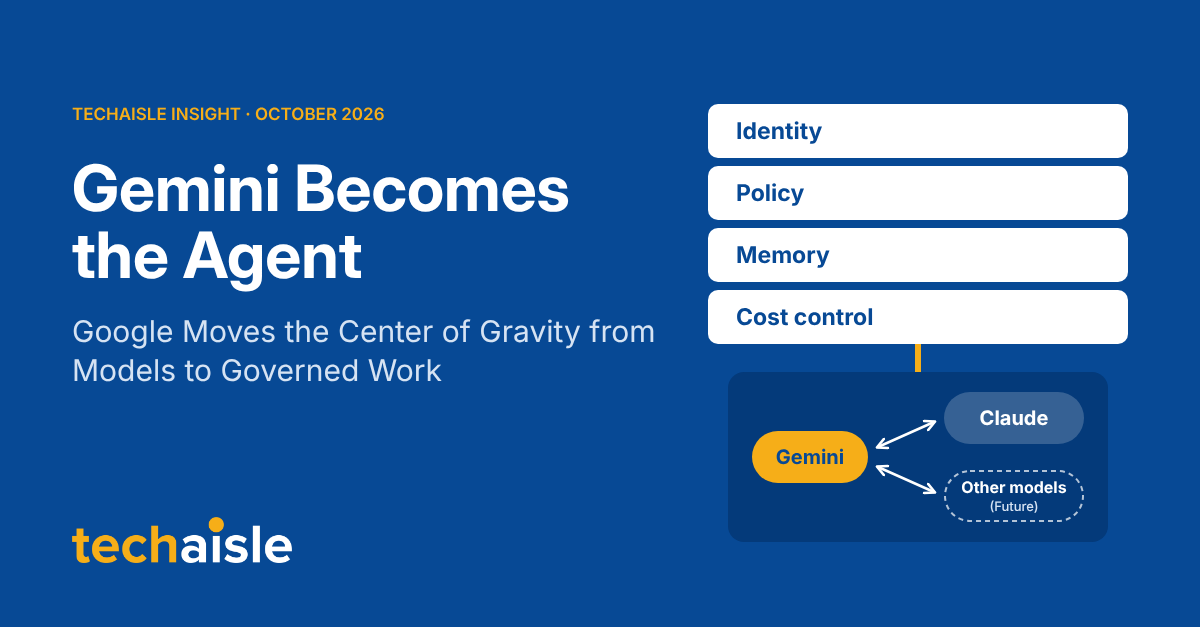
Google's Gemini at Work announcements put one agent, called Gemini, behind every surface a company uses. The agent is meant to be given an outcome rather than instructions, and to return finished work, running across a company's tools and systems for hours or days when the job needs it. Google also separated the agent from the model running underneath, so Gemini can hand a step to Anthropic's Claude when Claude is better suited, with other private and open models to follow. Google is competing on identity, policy, memory, and cost control, and treating the model as a part it is prepared to source from a rival.

Techaisle Insight, October 2026. Gemini Becomes the Agent: Google Moves the Center of Gravity from Models to Governed Work. Diagram showing four stacked layers labeled Identity, Policy, Memory and Cost control above a model slot, where Gemini connects to Claude and to other models planned for the future.

For firms with 1 to 10,000 employees, the market Techaisle tracks, model quality is rarely what holds agents back. The harder questions are whether agents stay affordable once usage scales, whether the CISO will let them run, and who will operate them, and Google's launch speaks to those more directly than its enterprise customer stories suggest.

Lock-in moves from the model to the context

Model leadership changes hands several times a year, and few customers want to rebuild their agents each time it does. Gemini's model choice addresses that risk: the agent picks the model for each step, today from Google's own Gemini family or Anthropic's Claude, with other models to follow. Google owns one of the best model families and still built Gemini so customers can choose another. That is a confident bet on the agent, and it works because the switching cost has moved to what the agent knows.

Techaisle Insight on Google Gemini at Work. Quote from Anurag Agrawal, Founder and Chief Global Analyst, Techaisle: Google owns one of the best model families and still built Gemini so customers can choose another. That is a confident bet on the agent. Photo of Anurag Agrawal beside the quote.

Google is connecting Gemini to its Knowledge Catalog, an existing Google Cloud service, so that every agent works from the company's own business definitions. The catalog holds one agreed definition for each business term and reads metrics from the systems where the company already maintains them. Gemini's memory runs from the task at hand to a record of how the organization does its work, and the agent writes some of its own skills as it goes. After a year of use, that body of definitions, history, and skills is far harder to move than a model is to swap.

Anurag Agrawal

The Absorption Test: What IBM Can Actually Sell to the Midmarket

On July 22, 2026, IBM told investors it is accelerating changes to its go-to-market model to expand sales coverage across thousands of additional clients where its portfolio is highly relevant and wallet share is available. It paired that with an investment in specialized technical and client-facing talent, including Forward Deployed Engineers. Arvind Krishna has been circling this idea for several quarters. He calls it the long tail. Read against firmographics, the long tail is the midmarket, with the upper band of small business attached to it.

Techaisle sizes worldwide IT spending by firms with 1 to 4,999 employees at US$1.667 trillion in 2026, with services taking the majority. This is the primary driver of commercial IT growth globally. It is also the market IBM has historically reached through partners, priced for enterprises, and packaged for buyers who employ platform teams.

Whether IBM wants this segment is settled. It has said so plainly and has now moved headcount and compensation to back it up. What remains open is which parts of a portfolio assembled across two decades of enterprise engineering can be consumed by a firm with 400 employees, 6 people in IT, and no platform team.

The Absorption Test

A product fits the long tail when it absorbs operating complexity instead of offloading it onto a team the buyer does not have.

IBM has made a version of this case itself. Rob Thomas, IBM's Chief Commercial Officer, has framed the central AI question as how you operate AI across everything you already have, and calls the approach an AI operating model. He is describing enterprises. The same logic binds harder one tier down, where there is no one to do the operating.

Most enterprise software fails this test in three ways. It needs a standing platform team to run, a configuration project before the buyer sees any value, and a procurement cycle longer than the payback window a midmarket CFO will tolerate. Any one of those is disqualifying. The configuration project is the quiet one, because it arrives as a budget line nobody planned for.

All three assume an IT organization with people to spare. The midmarket carries enterprise-shaped problems on a small-business-shaped bench. Techaisle’s SMB and Midmarket Datacenter Solutions Adoption Trends study, 2026, N=2,857, puts the execution constraint at 85% for talent and 65% for facilities, with 88% of firms reporting a partner expertise deficit. Techaisle’s GenAI adoption research finds 37% to 45% of midsized firms still inside Pilot Purgatory, funded and committed but unable to reach production. Midmarket organizations are allocating 17% of IT budgets to GenAI and planning a 27% increase, so the constraint is not money.
Techaisle Analyst Insight: The Absorption Test - What IBM can actually sell to the midmarket.

Tags:
IBM
Anurag Agrawal

What Amazon Connect Changes for Customer Service and the Midmarket

A customer stranded at a rental counter after a late flight calls for help and reaches a phone tree built to keep her away from a person for as long as it can. Press one. Press two. That system is not broken. It is working exactly as designed, because for 30 years the design goal of customer service was to reduce how often anyone reached a human, and the human was the expensive part. The same constraint shaped three other functions. Supply chain teams worked only the deviations they had hands for. Recruiters read only the resumes they had time for. Care teams followed up with only the patients they could reach. In each case the limit was the cost of a person, and in each case the work that did not get done was invisible to the company failing to do it.

The contact center is the only function in a company that measures itself on how often it avoids its own work. Deflection rate counts how often customers are kept out of a live conversation. Containment rate counts how often they are held inside a self-service loop. Both metrics were rational under the old cost structure. Amazon Connect Customer treats them as the wrong measures and replaces them with a single question: whether the customer’s problem was solved.

Techaisle quote card on Amazon Connect Customer: contact centers scored themselves on how often they avoided their own customers. Now the only score is whether the problem got solved. Anurag Agrawal, Founder and Chief Global Analyst, Techaisle.

Trusted Research | Strategic Insight

Techaisle - TA