• TRUSTED RESEARCH

    TRUSTED RESEARCH | STRATEGIC INSIGHT

    SMB. CORE MIDMARKET. UPPER MIDMARKET. ECOSYSTEM
    LEARN MORE
  • COMMS, COLLAB, CONTACT CENTER

    COMMS, COLLAB, CONTACT CENTER

    SMB & Midmarket Buyers Collaboration, Contact Center Study
    LATEST RESEARCH
  • DATACENTER SOLUTIONS

    DATACENTER SOLUTIONS

    SMB & Midmarket Datacenter Solution Adoption Trends
    LATEST RESEARCH
  • PARTNER ECOSYSTEM

    PARTNER ECOSYSTEM

    CHANNEL PARTNER ECOSYSTEM TRENDS STUDY
    LATEST RESEARCH
  • BUYER JOURNEY

    BUYER JOURNEY

    SMB & Midmarket Buyers Journey Research
    LATEST RESEARCH
  • BUYER PERSONAS

    BUYER PERSONAS

    SMB & Midmarket Technology Buyer Persona Research
    LATEST RESEARCH
  • ARTIFICIAL INTELLIGENCE

    ARTIFICIAL INTELLIGENCE

    SMB & Midmarket Analytics & Artificial Intelligence Adoption
    LATEST RESEARCH
  • IT SECURITY TRENDS

    IT SECURITY TRENDS

    SMB & Midmarket Security Solutions Adoption Trends
    LATEST RESEARCH
  • 2026 TOP 10 SMB BUSINESS ISSUES, IT PRIORITIES, IT CHALLENGES

    2026 TOP 10 SMB BUSINESS ISSUES, IT PRIORITIES, IT CHALLENGES

  • 2026 TOP 10 SMB PREDICTIONS

    2026 TOP 10 SMB PREDICTIONS

    SMB & Midmarket: Autonomous Business
    READ
  • 2026 TOP 10 PARTNER PREDICTIONS

    2026 TOP 10 PARTNER PREDICTIONS

    Partner & Ecosystem: Next Horizon
    READ

Techaisle Analyst Insights

Trusted research and strategic insight decoding SMBs, the Midmarket, and the Partner Ecosystem.
Anurag Agrawal

Lenovo AI Express Puts a Date on Midmarket AI

For most of the past two years, a midmarket firm that decided to run AI on its own infrastructure faced an awkward wait. It could approve the budget, pick the use case, and win over the CFO, then wait months, sometimes close to a year, for the GPU servers to arrive. By the time the hardware landed, the business case had aged, and the sponsor had often moved on.

Lenovo AI Express goes after that wait directly. Customers choose one of three validated Lenovo Hybrid AI Factory configurations built with NVIDIA, and Lenovo commits to order-to-ship in 15, 20, or 25 business days. Lenovo built the program for customers of every size, from SMB to enterprise. I focus on the midmarket here because that is where a delivery date changes the most.

For a midmarket buyer, that date matters more than anything on the data sheet. An AI project in a firm of this size usually rests on one sponsor and one budget cycle, and a delivery date lets that sponsor show results inside the fiscal year that funded the purchase. That is often what separates a second phase from a canceled one. Plenty of vendors have built AI reference designs, so the contest has been about who has the best architecture. Lenovo is the first I have seen put a delivery date at the front of the sales conversation, which moves the contest to who can actually deliver.
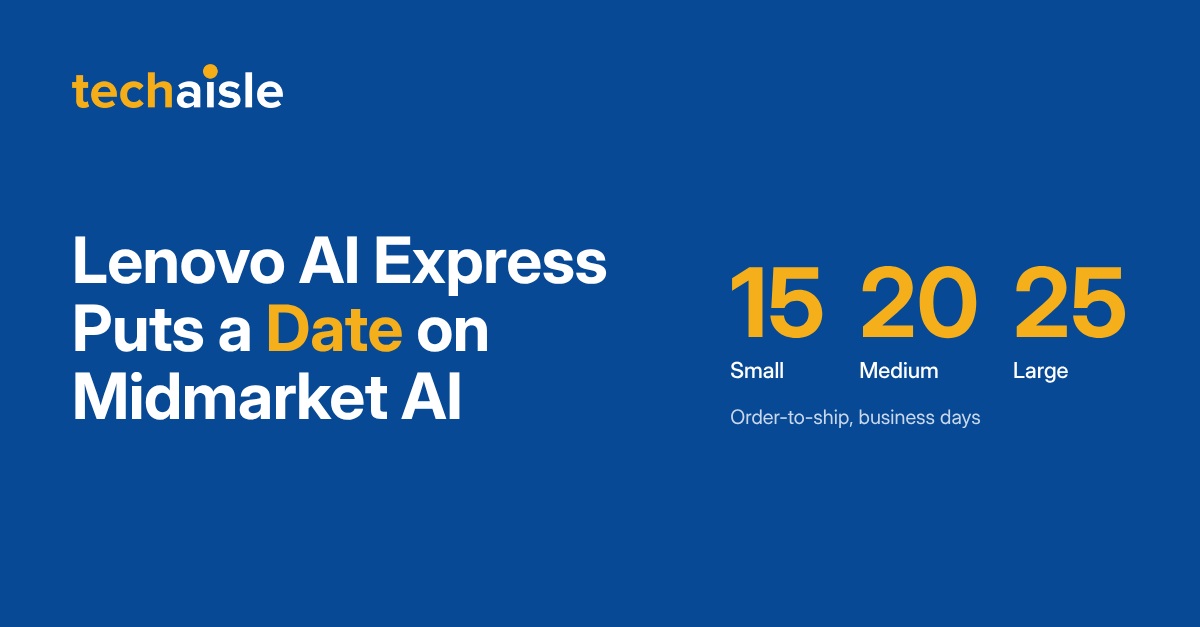
Lenovo AI Express Puts a Date on Midmarket AI: order-to-ship in 15, 20 or 25 business days for Small, Medium and Large

Tags:
Anurag Agrawal

Lenovo's Estate Advantage: What the World Cup Proved and the AI PC Debate Keeps Missing

Key Takeaways

  • The advantage is not the AI PC itself. It is the breadth of device categories Lenovo can integrate and manage through a common software and services layer, which is what lets a single agent work across an entire fleet. A vendor focused primarily on PCs has fewer categories to work across.
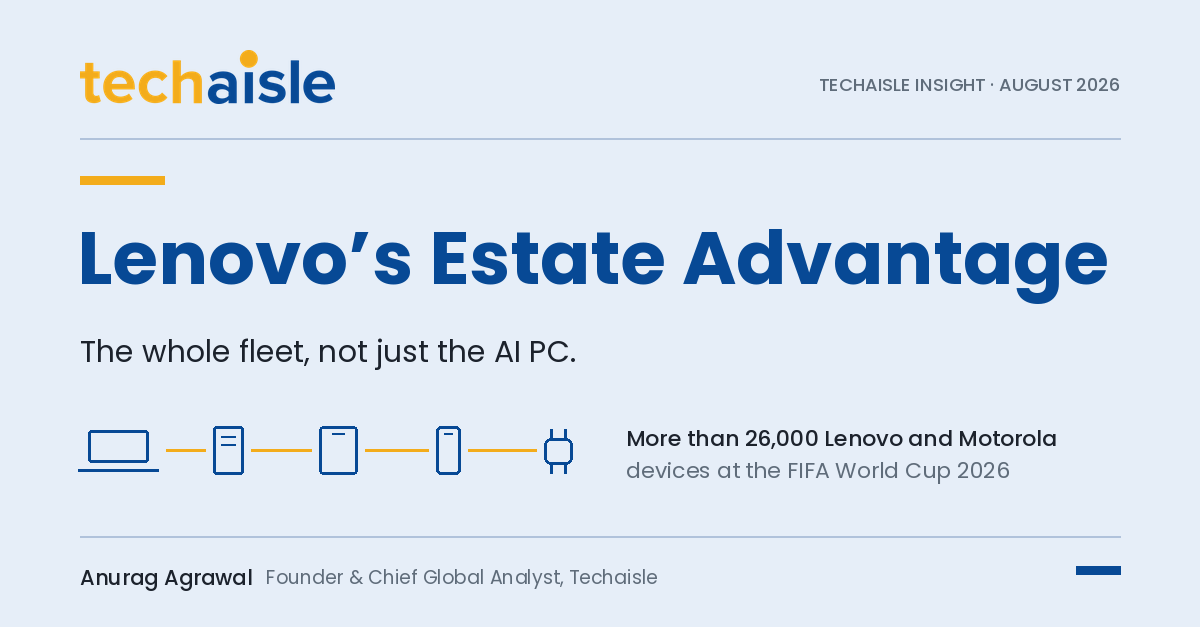
  • The FIFA World Cup 2026 proved the model at scale. More than 26,000 Lenovo and Motorola devices across three countries, deployed and managed as one fleet, with FIFA highlighting Lenovo’s rapid deployment and managed lifecycle approach as helping accelerate operational readiness in weeks rather than months.
  • The constraint is go-to-market, not portfolio. MSPs influence 61% of SMB PC decisions, yet only 34% of SMBs say their MSP explains the business value of an AI PC. Closing that gap is the highest-return move available to Lenovo today.

For the past two years, almost every conversation I have had about the AI PC has been a conversation about a single device. How many TOPS. Which NPU. How the battery holds up running a model locally. Vendors brief on it, partners repeat it, and buyers listen politely before asking the only question they actually care about: what any of this does for their business on Monday morning.

I have come to think the industry has been measuring the wrong thing, and that the mistake is more basic than any argument about silicon. We keep asking a single device to deliver value that is not created on a single device. Almost nobody does their job on one screen anymore.

Watch how a piece of work moves through a company today. A proposal gets drafted on a laptop, discussed in a message thread on a phone, approved on a tablet in the back of a taxi, and then picked apart the following week on a workstation by someone in finance who was never in the original meeting. No single device holds that story. The work lives across all of them, and so does the context that explains it.

techaisle lenovo estate

That distinction matters enormously once you put an AI agent into the picture, because an agent is only as useful as the context it can actually reach. An agent that lives on the laptop and nowhere else is reasoning about a fraction of what happened. It will summarize the document but miss the decision, because the decision was made on the phone. Techaisle research consistently shows buyers reporting the same frustration in different words, and it is the reason so many AI PC deployments have been underwhelming in practice even when the hardware was perfectly capable.

"We keep asking a single device to deliver value that is not created on a single device," Anurag Agrawal .

Anurag Agrawal

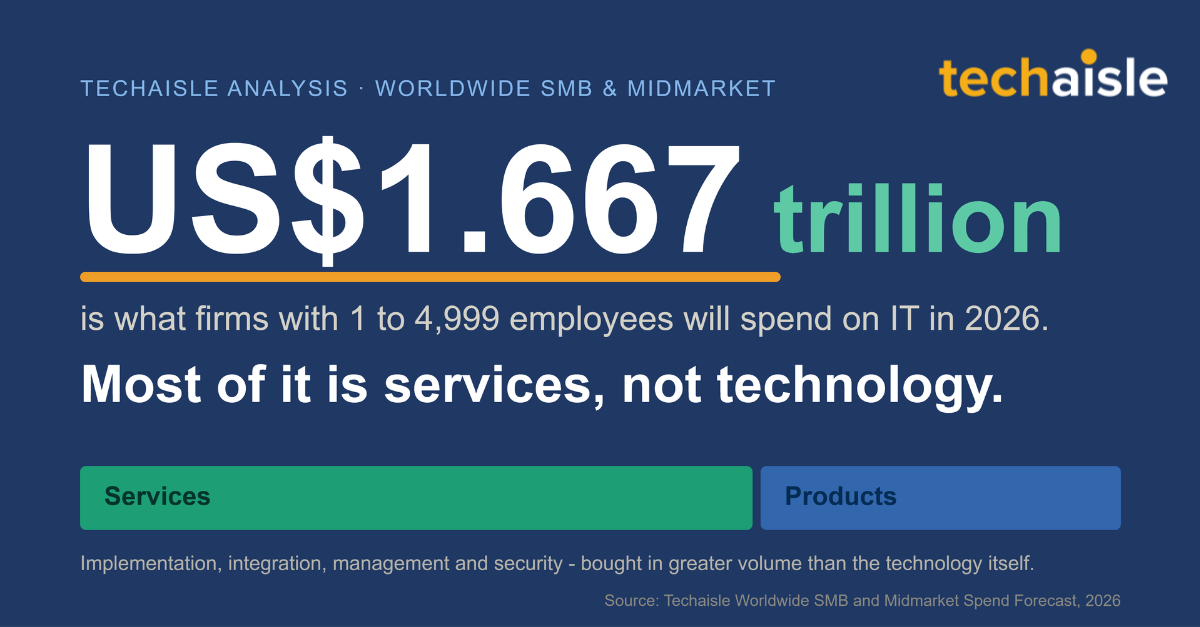
US$1.667 Trillion: WW SMB and Midmarket IT Spend in 2026

Worldwide IT spending by firms with 1 to 4,999 employees will reach US$1.667 trillion in 2026, excluding communication services, and the majority of it will go to IT services rather than to technology products. A market of that size, spread across every economy and every industry, sets the direction for commercial IT rather than following it. These firms are now spending more on the implementation, integration, management, and security of technology than on the technology itself, and the margin between the two is wide and widening.

That composition is the product of two forces working against each other. AI is pulling money up and forward, into software, infrastructure, and services that were not in the budget a year ago. Cost is pulling the other way, as component inflation, tighter budgets, and a higher cost of capital are pushing firms to defer what they can and to rent what they cannot. That second force is the quieter one, and it explains the tilt toward services better than any capability argument does. Buying an outcome instead of an asset moves cost from the balance sheet to the income statement, and it moves operational risk from the firm to the provider. In a year of expensive capital and unforgiving threats, that trade is worth paying for, which is why the money is moving toward services even where the technology itself is cheap.

techaisle smb midmarket it spend 2026

Within services, the mix has shifted. Maintenance, support, and break-fix, the labor of keeping systems alive, once defined the SMB services market. The money is now concentrating in consulting, integration, and putting AI into production. Transformation work has overtaken recurring management, and it is not close.

Anurag Agrawal

The Midmarket Is Buying Hardware to Escape Software

Ask a midmarket IT leader why they refreshed their servers this year, and the honest answer increasingly has nothing to do with the servers. It has to do with an invoice. Across Techaisle's SMB and Midmarket Datacenter Solutions Adoption study of 2,857 SMBs and Midmarket firms, a pattern surfaces that should change how every infrastructure vendor writes its pitch: capital expenditure on silicon is being deployed as a deliberate instrument to shrink operating expenditure on software licenses, cloud egress, and power. The physical box has become the cheapest variable in the equation, and buyers are treating it accordingly.

This is the quiet inversion of 2026. For most of the past decade, hardware was the thing you bought, and software was the thing that ran on it. In the midmarket, that relationship has flipped. The licensing model now dictates the silicon.

Broadcom made the invoice visible

The forcing function was the VMware licensing transition. Under the shift to subscription and per-core models, 52% of the upper midmarket reports a significant impact, which, in the study's language, means substantial cost increases or outright forced architectural changes. This is what a real forcing function looks like. A software pricing decision made in one company's boardroom is now rewriting the compute architecture of thousands of others.

What makes the finding interesting is not the pain. It is the response. Midmarket IT leaders did not passively absorb the increase. Only 14% of the upper midmarket is accepting the new subscription cost as a cost of doing business. The rest are re-architecting to get out from under it, and the exits they are choosing reveal a level of financial sophistication that the "SMB" label badly undersells.

Density as a defense

Tags:

Trusted Research | Strategic Insight

Techaisle - TA