• TRUSTED RESEARCH

    TRUSTED RESEARCH | STRATEGIC INSIGHT

    SMB. CORE MIDMARKET. UPPER MIDMARKET. ECOSYSTEM
    LEARN MORE
  • COMMS, COLLAB, CONTACT CENTER

    COMMS, COLLAB, CONTACT CENTER

    SMB & Midmarket Buyers Collaboration, Contact Center Study
    LATEST RESEARCH
  • DATACENTER SOLUTIONS

    DATACENTER SOLUTIONS

    SMB & Midmarket Datacenter Solution Adoption Trends
    LATEST RESEARCH
  • PARTNER ECOSYSTEM

    PARTNER ECOSYSTEM

    CHANNEL PARTNER ECOSYSTEM TRENDS STUDY
    LATEST RESEARCH
  • BUYER JOURNEY

    BUYER JOURNEY

    SMB & Midmarket Buyers Journey Research
    LATEST RESEARCH
  • BUYER PERSONAS

    BUYER PERSONAS

    SMB & Midmarket Technology Buyer Persona Research
    LATEST RESEARCH
  • ARTIFICIAL INTELLIGENCE

    ARTIFICIAL INTELLIGENCE

    SMB & Midmarket Analytics & Artificial Intelligence Adoption
    LATEST RESEARCH
  • IT SECURITY TRENDS

    IT SECURITY TRENDS

    SMB & Midmarket Security Solutions Adoption Trends
    LATEST RESEARCH
  • 2026 TOP 10 SMB BUSINESS ISSUES, IT PRIORITIES, IT CHALLENGES

    2026 TOP 10 SMB BUSINESS ISSUES, IT PRIORITIES, IT CHALLENGES

  • 2026 TOP 10 SMB PREDICTIONS

    2026 TOP 10 SMB PREDICTIONS

    SMB & Midmarket: Autonomous Business
    READ
  • 2026 TOP 10 PARTNER PREDICTIONS

    2026 TOP 10 PARTNER PREDICTIONS

    Partner & Ecosystem: Next Horizon
    READ

Techaisle Analyst Insights

Trusted research and strategic insight decoding SMBs, the Midmarket, and the Partner Ecosystem.
Anurag Agrawal

What Amazon Connect Changes for Customer Service and the Midmarket

A customer stranded at a rental counter after a late flight calls for help and reaches a phone tree built to keep her away from a person for as long as it can. Press one. Press two. That system is not broken. It is working exactly as designed, because for 30 years the design goal of customer service was to reduce how often anyone reached a human, and the human was the expensive part. The same constraint shaped three other functions. Supply chain teams worked only the deviations they had hands for. Recruiters read only the resumes they had time for. Care teams followed up with only the patients they could reach. In each case the limit was the cost of a person, and in each case the work that did not get done was invisible to the company failing to do it.

The contact center is the only function in a company that measures itself on how often it avoids its own work. Deflection rate counts how often customers are kept out of a live conversation. Containment rate counts how often they are held inside a self-service loop. Both metrics were rational under the old cost structure. Amazon Connect Customer treats them as the wrong measures and replaces them with a single question: whether the customer’s problem was solved.
Techaisle quote card on Amazon Connect Customer: contact centers scored themselves on how often they avoided their own customers. Now the only score is whether the problem got solved. Anurag Agrawal, Founder and Chief Global Analyst, Techaisle.

Anurag Agrawal

SMB and Midmarket Firms Are Buying More Meeting-Room Hardware as They Grow, Not Less

Hardware spend rises as companies scale, which runs against the assumption that software absorbs everything. Techaisle's study of 3,980 organizations shows where the laptop-and-dongle room breaks, what replaces it, and why the equipment is no longer there to show a meeting but to record one.

Almost every company starts the same way. A screen, a dongle, and whoever's laptop is in the room. It costs nothing, and it works well enough, which is why nobody ever decided to do it. Then, somewhere between the fifth room and the fiftieth, companies stop, and in Techaisle's survey of 3,980 organizations, the switch shows up in spending. USB add-ons for the laptop-and-dongle room fall to 18% at the top of the midmarket, the lowest priority on the whole list, while AI cameras, ceiling microphones, and sensors climb fast. The question worth answering is what they buy instead, and what forced the switch.

What the midmarket is actually buying

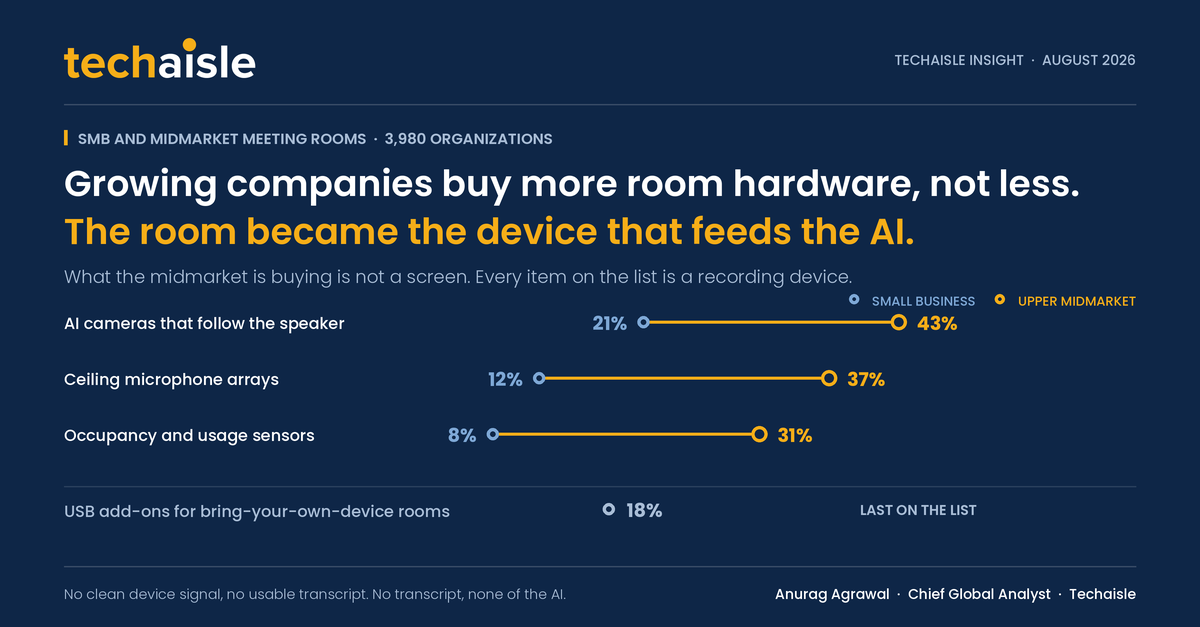
All-in-one video bars lead at every size, from 42% in the smallest firms to 56% in the largest, because they work the moment you switch them on. That part is expected. The next tier of spending is less so. AI cameras that follow the speaker rise from 21% to 43%. Ceiling microphone arrays climb from 12% to 37%. Sensors that count people and track how a room is used go from 8% to 31%.

Techaisle chart showing meeting room device priorities rising with company size: AI cameras from 21% to 43%, ceiling microphone arrays from 12% to 37%, and occupancy sensors from 8% to 31%, while USB add-ons for laptop-and-dongle rooms sit last at 18%.

Anurag Agrawal

SMB and Midmarket Contact Centers Keep Losing Their Agents. AI's Real Job Is to Fix That.

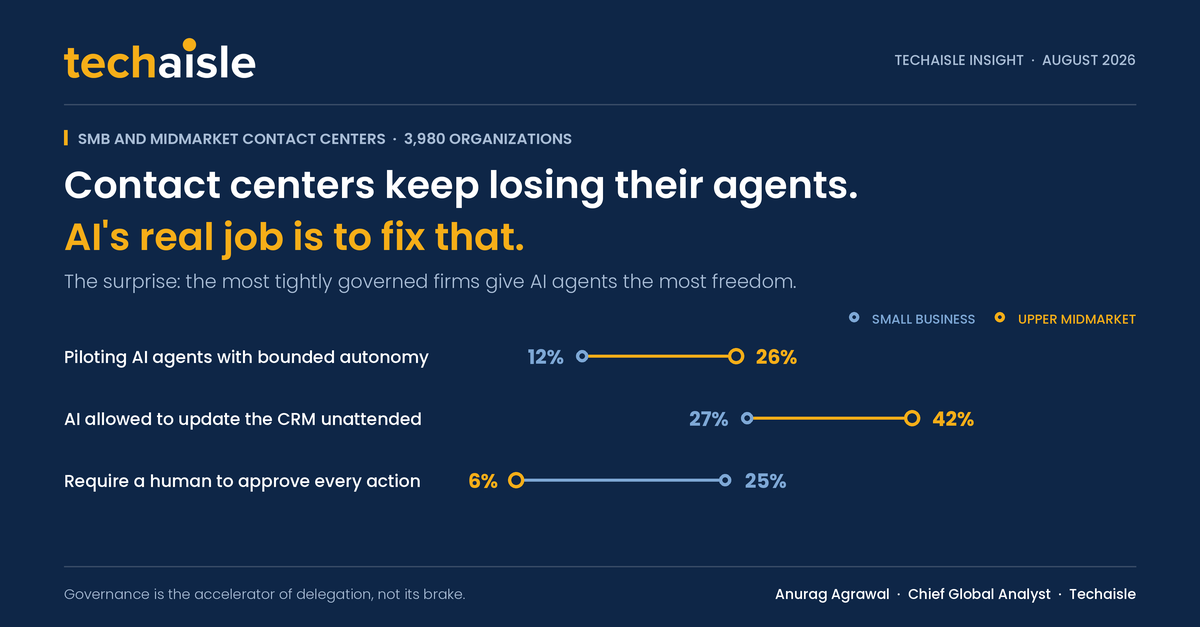
Attrition, not missing features, is the contact center's real problem. Techaisle's study of 3,980 organizations shows the fix is a governed AI workforce. The surprise: the most tightly controlled companies give their AI agents the most freedom.

Ask a contact center manager what their hardest operational problem is, and the answer is rarely a software gap. It is that agents keep quitting. In Techaisle's data, attrition is the single biggest challenge contact centers report. The cost of running the operation, the thing most vendors pitch against, actually fades as a worry as companies grow, from 47% of firms citing it down to 16%. The contact center looks like a technology problem. It is a staffing problem wearing a technology budget.

Techaisle chart showing how AI agent autonomy in SMB and midmarket contact centers changes with company size: bounded autonomy pilots rise from 12% to 26%, unattended CRM updates rise from 27% to 42%, and the requirement for human approval of every action falls from 25% to 6%.

The workforce is getting harder to manage

The contact center is the fastest-growing part of the communications market. Agents rise from 4% of the workforce in the smallest firms to 14% in the largest; about 70% of midmarket companies run more than 100 agents, and the real budgets appear in the 100-to-999-employee range.

The work is not going away. Inbound phone calls stay near-universal, at 90% to 95%, so the call is still the core of the job. What changes is where the people sit. More agents work from the office again, up from 43% to 58%, and more work is handed to outside firms, with outsourcing rising from 12% to 33% and offshore staffing from 8% to 30%. A midmarket contact center is now running a workforce that is bigger, more scattered, more outsourced, and still walking out the door. A longer feature list fixes none of that.

The fixes that help, and the one that matters

Anurag Agrawal

The Meeting Is the Most Cancelable Thing You Sell: Where SMB and Midmarket Collaboration and Video Stickiness Actually Live

Meetings are the flagship surface and the first line item cut when cash tightens. Techaisle's study of 3,980 SMB and midmarket organizations identifies the real moat in something less glamorous: the phone number, the call history, and the ability to find what was decided.

A standalone meetings subscription is the easiest thing in the software stack to cancel. It is duplicated free inside the productivity bundles most firms already pay for, it carries an obvious monthly price, and nothing breaks when it disappears. In Techaisle's survey of 3,980 small business and midmarket organizations, that fragility is not a small-business quirk. It is the structural weakness sitting at the center of the collaboration category, and most meetings-first roadmaps are aimed in the wrong direction because of it.

Start with what no longer wins. File sharing, messaging, and productivity-suite integration still dominate the list of capabilities buyers rate critical, at 46% to 56%. That is precisely why they no longer close deals. A capability that every competitor ships and every bundle includes is table stakes, not differentiation. The base of the collaboration stack has commoditized, and buyers now assume it the way they assume dial tone.

The instinct, when the base commoditizes, is to pile more features into the flagship. Another AI summary, another whiteboard, another in-meeting widget. The data says that instinct is a treadmill. Voice, video, and chat are universal across every company size. Adding a fourth in-meeting feature to a market that already has three of everything does not move a buyer, because the buyer's pain is no longer inside the meeting. It sits on either side of it.

techaisle meetings

The two unmet needs: find what was said, and meet less

Two problems rise as firms scale, and neither is solved by a better meeting.

Trusted Research | Strategic Insight

Techaisle - TA