• TRUSTED RESEARCH

    TRUSTED RESEARCH | STRATEGIC INSIGHT

    SMB. CORE MIDMARKET. UPPER MIDMARKET. ECOSYSTEM
    LEARN MORE
  • COMMS, COLLAB, CONTACT CENTER

    COMMS, COLLAB, CONTACT CENTER

    SMB & Midmarket Buyers Collaboration, Contact Center Study
    LATEST RESEARCH
  • DATACENTER SOLUTIONS

    DATACENTER SOLUTIONS

    SMB & Midmarket Datacenter Solution Adoption Trends
    LATEST RESEARCH
  • PARTNER ECOSYSTEM

    PARTNER ECOSYSTEM

    CHANNEL PARTNER ECOSYSTEM TRENDS STUDY
    LATEST RESEARCH
  • BUYER JOURNEY

    BUYER JOURNEY

    SMB & Midmarket Buyers Journey Research
    LATEST RESEARCH
  • BUYER PERSONAS

    BUYER PERSONAS

    SMB & Midmarket Technology Buyer Persona Research
    LATEST RESEARCH
  • ARTIFICIAL INTELLIGENCE

    ARTIFICIAL INTELLIGENCE

    SMB & Midmarket Analytics & Artificial Intelligence Adoption
    LATEST RESEARCH
  • IT SECURITY TRENDS

    IT SECURITY TRENDS

    SMB & Midmarket Security Solutions Adoption Trends
    LATEST RESEARCH
  • 2026 TOP 10 SMB BUSINESS ISSUES, IT PRIORITIES, IT CHALLENGES

    2026 TOP 10 SMB BUSINESS ISSUES, IT PRIORITIES, IT CHALLENGES

  • 2026 TOP 10 SMB PREDICTIONS

    2026 TOP 10 SMB PREDICTIONS

    SMB & Midmarket: Autonomous Business
    READ
  • 2026 TOP 10 PARTNER PREDICTIONS

    2026 TOP 10 PARTNER PREDICTIONS

    Partner & Ecosystem: Next Horizon
    READ

Techaisle Analyst Insights

Trusted research and strategic insight decoding SMBs, the Midmarket, and the Partner Ecosystem.
Anurag Agrawal

Look back on US SMB PC purchase intentions

Look back

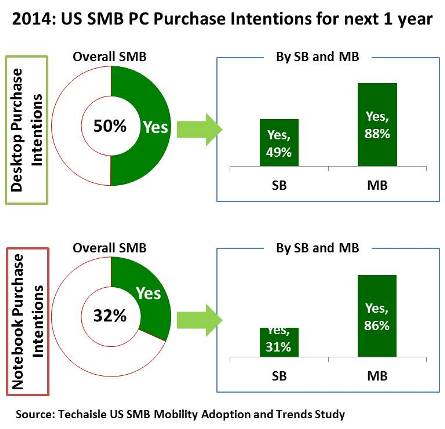
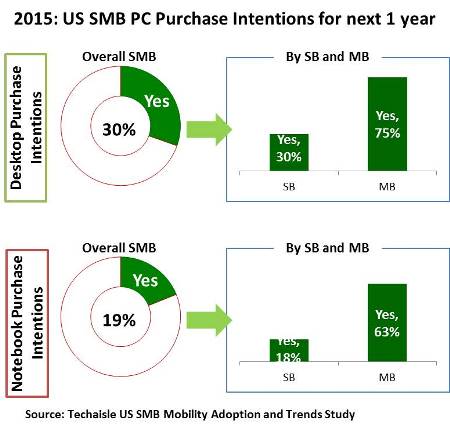
As is the case in each year’s SMB research, Techaisle SMB survey respondents are asked to detail their plans for acquisition of different types of client devices. Two of the major categories investigated by the surveys are desktop PCs and notebook PCs. To establish a baseline understanding of PC use and demand, Techaisle asks SMB respondents to specify the number of endpoint devices that are currently in use within their companies, and then asks them to specify the quantity that they are planning to buy over the next twelve months. To provide actionable insight to our clients, the question asks separately about desktop PCs, notebook PCs and tablets. While 2016 survey is in the field it is worth looking at the trends of last two years. In 2014, both the US small and midmarket businesses were bullish about new desktop and notebook purchases. But in 2015, the percent of US SMBs planning to buy PCs had dropped by 40% from 2014 for both desktops and notebooks. However, although the average number units of desktops planned to purchase dropped from 2014 to 2015 the average number of notebooks planned to purchase increased substantially from 2014 to 2015.

2014-us-smb-pc-purchase-intentions-techaisle

2015-us-smb-pc-purchase-intentions-techaisle

Many desktop buyers were motivated to replace existing units because they were reaching end-of-life and take advantage of Windows XP upgrade path. Desktops are also more of a planned/budgeted item than other client form factors (notebooks, tablets), meaning that desktop acquisitions are more likely to appear in formal purchase plans than the mobile units, and less likely to be acquired on an ad hoc basis. Notebooks are usually ad hoc purchase items – meaning that they would be underrepresented in research of this sort relative to desktops. Additionally many users upgrade their notebooks over time (to replace damaged units, to get features like touchscreen, to obtain lighter or smaller products, etc.).

However, corporate purchase intentions do not provide a complete perspective on mobile device acquisitions.

Potential Impact of BYOD on US SMB PC Purchases

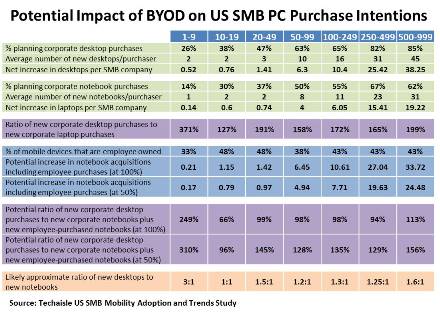
Figure below presents a perspective on corporate purchase plans and the impact of employee purchases of notebooks. The top two sections of the table, shaded in green, illustrate the proportion of businesses by employee size reporting desktop and/or notebook purchase intentions, and the number of units that they plan to acquire. These figures are used to prepare a “net increase” figure – the average number of new units expected to be deployed by businesses in each employee size category. These two grey sections are followed by a line of percentages, shaded in purple, which shows the ratio of corporate desktop purchases to corporate notebook acquisitions. It shows that microbusinesses with 1-9 employees are much more likely to be buying desktops than notebooks, and that other SMBs are planning to buy 25% to 99% more desktops than notebooks.

potential-impact-of-byod-on-smb-pc-purchase-intention-techaisle

The next section of the table, shaded in blue, begins with the BYOD penetration statistics that appear at the bottom of the figure. It then calculates the impact on notebook purchase intentions if this ratio is fully reflected in notebook purchases (the “at 100%” line) and if employees were to buy notebooks at half of the BYOD penetration rate (“at 50%), showing both corporate and employee purchases of these devices. These revised figures are used to calculate the desktop to notebook PC purchase proportions shown in the second set of purple-shaded cells. Here, we see that if employee purchases of notebooks are equivalent to current BYOD penetration levels, new notebook units would be about equal to new desktop purchases in most employee size segments, while a 50% scenario would result in ratios ranging from about 1:1 to 1:6 in all but the smallest employee size category.


Anurag Agrawal

Small Business Computing: Dell Hits the Mark with Vostro V131 Laptop

Dell continues to show that it is serious about small businesses. In an economy where consumer purchases are slowing down, small businesses are continuing to refresh their technology and are showing growth rate in IT spends.

Dell today introduced the Vostro V131, a thin, powerful, and sleek laptop designed specifically for small businesses. It is an ultrathin laptop housing Intel® Core i3 or i5 processors, geared towards maximizing small business productivity. A removable 6-cell battery with 2nd generation Intel Core processors, both available as an option, is expected
to deliver up to 9.5 hours of battery life, allowing SMB users to work virtually anytime, anywhere.

Techaisle’s small business survey shows that not only enhancing IT is important for small businesses but also improving productivity through automation is extremely important. Among the newer technologies that they are currently investing in include: Windows 7, refresh of PCs and servers, as well as smart phones. It is quite clear that small businesses are seriously looking at enhancing their IT infrastructure, migrating from older technologies to more modern hardware platforms are key initiatives for reducing cost of operations. Over 60% of small businesses think that it is time for a refresh of their PCs and servers. To that extent, the timing for the introduction of Vostro V131 could not be any better.

Not only is Vostro V131 designed for improved productivity and enhanced mobility as
repeatedly by small businesses, but the laptop has also addressed the need for data security and backup. Remote back up and disaster recovery is still a top of the mind IT initiative for small businesses.

The Vostro V131 has very useful collaboration options including a full HD camera, SRS Premium Voice Pro, digital array mics and built-in Skype. In addition, the laptop offers two USB 3.0 ports, a chiclet keyboard with a backlit option, and quick launch keys. These additional collaboration features play extremely well into the new small business workplace scenario. Techaisle’s small business mobility report shows usage of relevant collaboration applications used by SMBs when traveling.

Of the options available in My Business Toolkit, that comes loaded on V131 (from September onwards), the most appropriate and useful for a small business are the Ruby Receptionists, a virtual reception service and Trend Micro Worry-Free Business Security Services.

Speaking about the announcement, Sam Burd, Vice-President of Dell’s Consumer & SMB Product Group said, “We designed the Vostro V131 to deliver fast, uninterrupted multitasking for today’s business challenges, the result is a feature-rich laptop for mobile professionals who want full performance to support their technology demands without sacrificing design and portability. In addition, the V131 offers services and software solutions that improve productivity and data security.”

V131’s starting price available on Dell.com is US$499 with a Celeron processor and a backlit keyboard which is a great price for a small business. An i3 based model is available for US$599. The price point is even better for small business owners that may be contemplating using Tablets instead of notebooks. V131 not only serves as a great content creator but also a secure and reliable collaboration tool while enhancing productivity.

We fully recommend it.

Anurag Agrawal
Techaisle

Anurag Agrawal

Smartphone to Notebooks Continuum: OS Wars and the Battle for Dominance

There is a continuum from smartphones to notebooks, with a variety of sizes and operating systems. The market will continue to be in a state of flux for several years before showing any signs of stable continuum.

    • Widespread adoption of cloud-based apps as well as VDI will make the OS and form factor comparatively less important


    • Apple will continue to have the “cool” factor in its favor, especially for those using non-office apps


    • While most vendors have not been able to match Apple’s cost/price advantage (which continues to exist despite its cool factor). However, this will change as Nokia (along with new vendors from low cost economies) begin to manufacture mobile devices in large numbers at low prices


    • Android developers have had the flexibility of implementing their own versions of Android (in order to distinguish themselves) although this is like to become less of a factor in the future but that itself becomes a problem of consistency and uniformity


    • Apple’s advantage in terms of no. of apps will soon diminish due to several factors:

        • Of the hundreds of 1000s of apps, only a few hundred bring in majority of revenues. Most Apple ISVs are part-time developers or unprofitable and will disappear from the market

        • The vast number of Windows-based apps developers will quickly adapt their apps to Windows mobile, diminishing Apple’s apps advantage and give businesses more relevant business-related apps

        • While currently, the focus is on horizontal apps, vendors will find it increasingly important to develop vertical apps  to expand the user base and obtain higher margins


    • Businesses will need to support multiple devices/mobile operating systems – making remote mobile device management an expanding market. Telcos, hosting companies and channel partners will play an important role in enabling that support


    • Additionally, synching up different devices will also become more important and VDI will help in achieving that objective


It is too early to project future shares of various device forms and mobile operating systems as the market will continue to be in a state of flux in the next few years. We cannot write off Microsoft Mobile or Nokia. They will helped due to their vast size and resources, deep commitment and large number of users/developers.

On the other hand, Android developers/devices are a varied lot, with each having a low share of the market. WebOS (Palm, now owned by HP) has some promise but it is unlikely to regain its glory days of late 90s. RIM is the most at risk due to the proliferation of new devices and mobile operating systems

Although smartphones have the potential of increasing their employee productivity, it will happen only for those employees who are smart enough themselves.

Anurag Agrawal
Techaisle

Anurag Agrawal

Intel’s SMB Strategy: Time to Re-ignite, Reboot?

SMBs are going through a Transformation, moving from a building block IT adoption to Flat IT in a virtual era. And within this Transformation, PC is still important in its role as the center of IT universe. SMBs need only buy a PC to get started. However, the nature and use of PC as the foundational block has changed. There is and will most likely remain only one block. An SMB today can start work immediately with a server that resides in the cloud, use smart phone that provides access to corporate information anytime and anywhere, a CRM application that resides off-premises, a communications infrastructure that is cost effective, a line of business application that is plug-and-play. All enabled by a simple credit card payment system and a PC.

Global SMB spend on IT is expected to be US$426 billion in 2011. PCs and Servers spend, core businesses of Intel, will be US$80 billion, resulting in 120 million PCs (Desktops & Notebooks) and 3.8 million servers. Despite the slowdown SMB market is still a very healthy market that requires focus and attention. Based on surveys in numerous countries, Techaisle finds that “Refresh of PCs and Servers” is among SMB priorities.

It is more important now than ever for Intel to hit harder at an SMB strategy and messaging.

Recognize Growing Influence of Retail
Importance of retail is continuing to increase across many countries as PCs increasingly become commoditized. 65 million PCs, half of total SMB PC shipments, are purchased by
1-20 employee size businesses that usually shop at retail stores. There are 186,818 dealers/retailers globally who derive 58 percent of their revenue from selling PCs. The retail channel is continuing to grow in number, especially in emerging markets. On the other hand there are 242,010 VARs/SIs globally who are increasingly moving into cloud offerings as they find their traditional services model getting threatened. Intel should work with its OEM partners to offer business SKU PCs through retail stores. A few of Intel’s OEM partners such as Dell have begun selling business SKUs through retail stores albeit in some countries. As compared to retail, VAR/SI channel derives 36 percent of their revenues from selling PCs. This only enhances the importance and influence of retail within the SMB segment for PCs. Intel should also open up vPro sales through all channels including retail. Similar to the messaging of i3, i5, i7, “with vPro” and “without vPro” will a good value proposition for SMBs and create a differentiation between SMBs and Consumers. As vPro adoption grows, different types of channels including neighborhood repair shops will have the motivation to jump in to provide remote support and services.

Facilitate Managed Services Adoption
Global SMB remote PC managed services is estimated to be US$1.3 billion in 2011 and will nearly double to US$2.5 billion in 2015. With vPro, Intel has a huge untapped opportunity to target managed services market aggressively. The technology has been around for a while and has had some success within enterprises. Selling vPro-based PCs through the non-retail channel to SMBs is certainly useful but selling through retail and white-box manufacturers will only quicken its adoption. The scenario today is similar to what the PC industry saw twenty years ago. To accelerate the adoption of PCs, Intel built a white-box channel and started shipping motherboards to them. Concerns were raised that the move would cannibalize market for traditional large OEM vendors but over a period of time both
OEM and white-box channels have learnt to co-exist. In fact there are 69,412 system builders across the world. Intel should be able build a similar program for white box assemblers with a focus on managed services using vPro. Large format retail channels could create their own NOCs or partner with other MSPs to offer remote managed support services (Techaisle had written about this happening in 2009, BestBuy purchasing mindShift has now happened). For small format retailers Intel should either create its own datacenter or allow OEM vendors to provide NOCs for remote managed support. Smaller system builders could use the data centers offered by Intel, its distributors or other large vendors for providing managed services to their SMB customers.

A PC Refresh Messaging – Path to Ultrabooks
Ultrabooks is another potential opportunity for Intel to sell into the SMB segment. However, current price point will inhibit adoption forcing Ultrabooks to be used primarily in corner offices and a smattering of traveling executives. If the price-point does not fall below US$800 this new form factor will follow the swift end like the netbook form factor. Ultra-thin aficionados will continue to adopt MacBook Air series. Initial adoption of netbooks had exposed a burning desire among Small Businesses for a low cost, light weight device with an extended battery life. At the same time huge adoption of tablets by SMBs as an additional device strongly suggests a market ripe for ultrabooks. However, a differentiated PC refresh messaging with Ultrabooks as mainstream notebooks PC is needed in the SMB marketplace. Although some may argue that VDI will replace PCs faster than PCs themselves, however, larger adoption of VDI among SMBs although growing in double-digits still too far in the future.

Cloud – Intel’s Small Business AppUp, Boon or Bane?
Among all of the new priorities that SMBs are driving towards, perhaps the one that most impacts the channel and the vendors is the trend towards increasing adoption of SaaS and Cloud Computing. All leading IT vendors – Microsoft, Dell, and IBM are providing a variety of cloud based platform and application services. Complementing them is a whole host of new companies that are aggressively developing solutions for this space. No doubt over the next 5 years cloud based services will be the new arena of intense competition. In
2011, SMB cloud computing spend will be US$11 billion (excluding spend on cloud
communication services). As SMBs transition investments driven by these new priorities, the impact on the channel will likely be significant. The small business AppUp services rolled out by Intel is certainly noble as it makes available best-of-breed cloud enabling technologies available to channel partners that serve small businesses. And it is easy to see why many cloud enabling technology vendors such as StorageCraft, GFI and many others will add their applications to the catalog. It gives them another distribution outlet. But
their continued commitment remains to be seen. However, Intel cannot just remain a Master Distributor, because it will very soon begin competing with its traditional distributors. More importantly, Intel in its effort to provide cloud services to its channels and small businesses is missing out on a very key issue: best-of-breed applications. No doubt the applications being offered are some of the best in the industry but there are too many of the same category. For example, how many backup and recovery applications will Intel offer before it finds that they are creating more confusion than simplicity? Channels
and SMBs will be forced to once again conduct their own research to sign up and use applications. It should not be a race for numbers but a race for best-of-breed. While its OEM partners may like to be part of the strategy initially they will not benefit in the long run. Within the next 2-3 years Intel’s OEM partners will begin to draw and implement their own SMB cloud strategies, most likely leaving behind Intel’s small business AppUp services.

Transition from IT vs. Non-IT
With growing adoption of cloud computing the role of IT has also been changing. Business departments are making procurement decisions independent of IT, similar to BYOD. In fact, Intel should focus its attention on Mobility vs. Non-Mobility or Cloud vs. Non-Cloud and even VDI vs. Non-VDI businesses. In effect, the old segmentation models do not exist anymore as the work from anywhere, anytime culture gets more ingrained within SMBs. Segments should be defined and labeled based on their business objectives.

Finally
Creating an SMB brand distinction is more important now than ever - a brand that delivers empowering technologies to both SMBs and their channel partners and a set of products and solutions that enable an SMB reach its full potential in the shortest period of time. SMBs will continue to invest in on-premise IT infrastructure while experimenting with, or moving selective applications to the cloud and increasing their reliance on MSPs. As SMBs prefer to procure their IT products and services from same channels Intel should evaluate all of its partners’ expertise areas and create symbiotic partnerships among them with Intel as the broker to serve the SMB customers. At the same time Intel should recruit new retail channel partners to advise, train and thereby help its OEM partners.

Anurag Agrawal
Techaisle

Trusted Research | Strategic Insight

Techaisle - TA